

Money Eco: Budget / Expense analysis by Appwee
Managing money sounds simple until everyday spending starts arriving from several directions at once. A coffee paid with a card, a cash purchase, a recurring bill, and an unexpected repair can make a monthly budget feel unclear very quickly. I tested Money Eco: Budget / Expense as a personal finance app built around recording expenses, organizing a budget, and turning that information into visual reports. Its main appeal is not complicated investing advice; it is giving ordinary spending a clearer shape.
Developed by Apponance, Inc., the app sits in the finance category and is free to install, with optional in-app purchases ranging from $0.99 to $14.99 per item. It is rated for Everyone, works on Android 7.0 or later, and the current version is 7.1.0. The store summary points to money management, budget tracking, and personal finance visualization, but my experience is that its real value depends on how consistently you feed it useful information.
Where Money Eco Gets Useful—and Where People Get Stuck
The first thing I noticed is that a budget tracker only becomes helpful after it reflects your actual habits. Money Eco is not a magic financial adviser that can repair an overspending pattern on its own. It gives you a place to record the pattern, sort it into understandable areas, and look back at the result. That makes it a good fit for someone who wants more awareness without committing to a complex financial planning system.
The most common point of friction is likely to be the first round of categorizing. A transaction such as a supermarket visit may contain groceries, household supplies, and an occasional nonessential purchase, but the app still needs one practical label for the entry. I found it more useful to choose a consistent category than to spend too much time chasing perfect precision. A budget becomes easier to read when similar purchases are treated similarly from one week to the next.
Another sticking point is the difference between recording an expense and understanding it. Entering a number can feel productive, but the useful moment comes later, when the visual report shows where the money went. I recommend using the reports as a review tool rather than checking them after every single purchase. Looking at a group of transactions makes small leaks easier to recognize than staring at isolated entries.
There is also a behavioral hurdle: manual tracking asks for attention. If I forget to enter several purchases, the report becomes incomplete and the budget can look healthier than it really is. That is not necessarily a flaw in the calculations; it is a consequence of missing input. Anyone choosing this app should be comfortable with a routine that takes a little discipline.
Start with a small, realistic budget
My advice is to begin with the spending areas that matter most in your daily life instead of trying to model every possible financial detail immediately. For example, someone trying to reduce food delivery costs can start by making that area easy to recognize. A student may care more about transport, meals, and entertainment, while a household may need a broader view of bills and shopping.
This approach reveals one of Money Eco’s practical strengths: it can make a narrow financial goal visible without forcing you to redesign your entire life. If the goal is to understand discretionary spending, the app can be used as a focused log for that purpose. Once the routine feels natural, adding more categories becomes less tiring.
A useful non-obvious habit is to record purchases close to the moment they happen, but postpone judgment until the review. If I label every transaction emotionally—“good,” “bad,” or “unnecessary”—I am more likely to abandon the process. Treating the app as a neutral record first produces a more honest picture. The report can then support a calmer decision about what to change.
Setup Checks Before You Trust the Reports
Before relying on any finance visualization, I would check the basic structure of the account or budget inside the app. Confirm that the starting balance or initial amount reflects the point at which you began tracking. If you start halfway through a month, the first report may not represent a complete period, so it should be treated as a baseline rather than a final judgment.
I would also decide how to handle cash. Card payments often leave a digital trail elsewhere, while cash purchases are easier to forget. If cash is part of your routine, recording it immediately is especially important. A budget report cannot infer a purchase that was never entered, and an apparently low spending total may simply reflect an incomplete record.
Categories deserve a deliberate check as well. Keep names and meanings stable. If restaurant meals are sometimes placed under food and sometimes under entertainment, the visual breakdown will be harder to interpret. Consistency is more valuable than creating a very detailed list that becomes annoying to maintain.
For recurring bills, I would use a simple calendar reminder outside the app if I tend to forget entry dates. Money Eco can organize the information I provide, but a finance tracker should not be treated as a replacement for every reminder or banking control. This is one of the important trade-offs compared with a bank app: a bank application may automatically show transactions from an account, while a manual budget tool can offer a cleaner personal view but depends more heavily on the user.
Device compatibility is straightforward for many Android users because the app supports Android 7.0 and newer. If the app behaves oddly during setup, I would first confirm that the operating system is supported, then close and reopen it, and finally check whether the app is updated to version 7.1.0. These are basic steps, but they prevent a user from confusing an outdated installation with a budgeting problem.
Use the first week as a calibration period
I would not set an aggressive savings target on the first day. Instead, I would spend the opening week learning how quickly entries can be made and which categories are genuinely useful. This creates a more realistic budget because it is based on observed behavior rather than an optimistic guess.
One practical workflow is to make a short note of purchases during the day and enter them together at a quiet time. That reduces interruptions, but it introduces a memory risk. A better compromise is to enter unusual or larger expenses immediately and batch only the predictable small purchases. This keeps the record accurate without turning every transaction into a separate task.
Another helpful check is to compare the total recorded spending with the balance you expect to have available. If the two do not make sense, do not immediately assume the app is calculating incorrectly. Look for a forgotten cash purchase, a duplicated entry, or a transaction placed in the wrong period. This simple reconciliation habit is more valuable than repeatedly changing categories until the chart looks comfortable.
Recovering a Budget When the Workflow Breaks
Most people will eventually miss several entries. When that happens, I would not delete the whole budget and start again. First, identify the last date that looks trustworthy. Then rebuild the missing period from the most reliable sources available to you, such as receipts, bank notifications, or a quick review of recent purchases. Enter the larger transactions first, because they have the greatest effect on the report.
If the totals still look strange, check for duplicates before changing the budget limits. A duplicated bill can make a category appear out of control, while a missing purchase can make another category look unusually healthy. Correcting the record is usually better than adjusting the target to hide the error.
When a category has become messy, I prefer a clear rule for future entries rather than trying to reconstruct every historical detail perfectly. For instance, decide that household cleaning products will always be treated as household spending, even if they were bought during a supermarket trip. The historical report may remain imperfect, but future comparisons will become meaningful.
This is where the visual reporting can be especially useful. A chart or summary is not just decoration; it can act as a diagnostic clue. A sudden spike may point to a real event, such as an annual payment, or it may expose a data-entry mistake. I would inspect the underlying transactions before making a financial decision based on a surprising visual result.
Keep recovery simple enough to repeat
A recovery process that takes an hour is unlikely to become a habit. I would use a short weekly review: check the latest entries, look for obvious omissions, and note one category that deserves attention. The goal is not to produce perfect accounts; it is to keep the information useful enough for the next decision.
For a realistic example, imagine that I buy lunch near work several times during a busy week, pay for a household item in cash, and receive a regular bill at the weekend. If I record only the bill, the report may suggest that my week was inexpensive. If I add the lunches and cash purchase later, the picture changes. The lesson is not simply “spend less”; it is that timing and completeness determine whether the report can help me.
People sharing finances should also agree on a recording routine. If one person enters expenses immediately and another waits until the end of the month, the report can become uneven. Money Eco is more useful when everyone who contributes to the budget follows the same basic category rules. If that coordination is unrealistic, a shared spreadsheet or a bank-centered tool may be more suitable.
When the App Is Not the Cause of the Problem
Finance apps are often blamed when the real issue is an unclear goal. If I set a monthly limit without considering irregular expenses, the result may look disappointing even when the app is working correctly. A yearly insurance payment, seasonal shopping, or a one-off repair can distort a short period. In that situation, the better response is to plan for irregular costs rather than expecting a monthly chart to make them disappear.
Connectivity can also create confusion when a user expects automatic banking behavior from a manual tracker. A bank app is usually the better choice for checking the official balance of an account. Money Eco serves a different purpose: it can help me interpret spending through my own budget structure. I would use the bank’s figures as the source of truth for account balances and the budget app as a planning and reflection layer.
Privacy expectations are another reason to choose carefully. Anyone who wants a completely automated financial dashboard, direct account synchronization, or a broad investment overview should compare other finance products before settling here. Money Eco is more appealing to someone who values a focused expense record and is willing to participate in the process.
The free price makes it easy to try without an upfront purchase, but optional in-app purchases mean that some users may encounter paid extras while exploring the app. I would decide early whether the basic workflow already solves my problem. If it does, there is no reason to buy something merely because it is available. If a paid item appears necessary for a feature I specifically want, I would check that it fits my preferred way of working before spending money.
The audience rating of Everyone also makes the app approachable for a broad range of users, but that does not mean every financial situation is equally well served. Someone managing business accounts, taxes, investments, debt repayment schedules, or multiple currencies may need specialized software. A simple personal expense tracker can support awareness, yet it should not be mistaken for professional accounting or financial advice.
Who should choose a different tool?
I would skip Money Eco if I know I will not record transactions regularly. In that case, an automatically connected banking service may reduce the effort, although it may offer less control over how spending is interpreted. I would also look elsewhere if my main goal is bill negotiation, investment management, credit monitoring, or detailed household collaboration.
On the other hand, I think it suits people who want to answer practical questions: How much did I spend in a particular area? Which habits are pushing the budget upward? Did this month feel expensive because of one unusual purchase or because small expenses accumulated? Those questions are concrete enough for a budget and expense tracker to address well.
The app has earned a 4.7 average from around fifty ratings, and it has passed ten thousand installs. Those figures suggest a modest but positive user footprint rather than the scale of a dominant financial platform. I would read that as a reason to judge the app by its workflow and fit, not by popularity alone.
My Practical Verdict After Using It
Money Eco: Budget / Expense works best as a clear, user-maintained record of personal spending. I like the idea of combining budget entry with visual reporting because it encourages a move from vague worry to specific observation. Instead of wondering where the money went, I can inspect the categories and decide which behavior deserves attention.
Its main limitation is also its central design trade-off: the quality of the result depends on the quality of the entries. That makes it less effortless than an automated banking dashboard, but it can also make the budget feel more intentional. I am not just receiving a feed of transactions; I am deciding how to understand them.
If you install it, I recommend starting with a small set of categories, recording cash promptly, checking for duplicates during a weekly review, and treating the first reporting period as calibration. Those four habits prevent most of the misleading conclusions a new user might draw from an incomplete budget. They also make it easier to tell whether the app genuinely fits your routine.
Apponance, Inc. has positioned this as a free finance app for money management, expense tracking, and personal finance visualization, and that description matches the experience without needing exaggerated promises. I would recommend it to someone who wants a straightforward personal spending routine and is willing to enter information consistently. I would not recommend it as a replacement for a bank app, accounting package, or investment service.
My final view is positive but practical: this is a useful companion for awareness, not a substitute for financial judgment. If seeing your own spending patterns is the goal, the reports can turn scattered purchases into something you can act on. If convenience means complete automation to you, another category of tool will probably be a better match.
Gallery
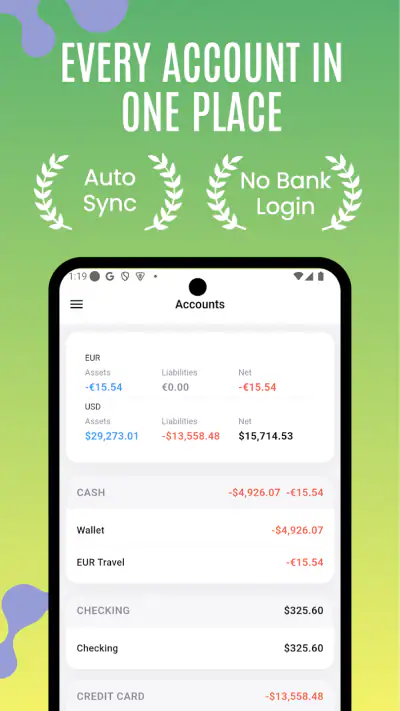
Money Eco: Budget / Expense Pros and Cons
- Simple interface makes daily expense tracking quick and approachable.
- Useful budget categories help organize spending by type.
- Clear summaries make it easier to spot spending patterns.
- Supports more mindful saving without requiring complex financial knowledge.
- Lightweight design should run smoothly on most modern mobile devices.
- May lack advanced investment and portfolio tracking features.
- Manual entry can become tedious for users with frequent transactions.
- Limited customization may not suit detailed budgeting systems.
- Some features or insights may require a paid upgrade.
- Users should review privacy settings before entering sensitive financial data.
Money Eco: Budget / Expense Frequently Asked Questions
What is Money Eco: Budget / Expense, and what can I use it for?
Money Eco: Budget / Expense is a personal finance app designed to help you record income, track daily spending, organize transactions into categories, and understand where your money goes. After testing its main features, it feels most useful for users who want a simple overview of their finances rather than a complex banking platform. You can use it to create a budget, monitor expenses, and develop better spending habits over time.
Is Money Eco: Budget / Expense suitable for beginners?
Yes, the app is generally suitable for beginners because its main purpose is straightforward: enter your income and expenses, then review the resulting summaries. The interface is easier to understand when you start with a few common categories, such as food, transport, bills, and entertainment. However, users who want advanced investment tracking, tax tools, or detailed financial planning may find the available budgeting functions more limited.
Does Money Eco: Budget / Expense connect to my bank accounts automatically?
Before downloading, users should check the current app description and privacy information to confirm whether automatic bank synchronization is supported in their country and version. Many budgeting apps require manual transaction entry, and this can be useful for privacy but less convenient for people with numerous purchases. If Money Eco does not support your bank, you should be prepared to add transactions yourself to keep the budget accurate.
Is my financial information safe when using Money Eco: Budget / Expense?
You should review the app’s latest privacy policy, permissions, and data-handling details before entering sensitive financial information. A budgeting app may store transaction descriptions, amounts, categories, or account-related data, depending on the features you use. Avoid sharing banking passwords or confidential details unless the app clearly explains secure authentication. Installing the official version from Google Play or the App Store is also important for reducing security risks.
Is Money Eco: Budget / Expense free to download, and are there in-app purchases?
The download price and available features can vary between Android and iOS, as well as across different updates. Check the official store listing before installing to see whether the app is completely free, supported by advertisements, or offers premium tools through subscriptions or one-time purchases. Also review the trial and renewal terms carefully, because advanced reports, extra budgets, cloud synchronization, or ad-free use may require payment.














